How to Start Investing in Index Funds With Just ₹500 in India
Introduction
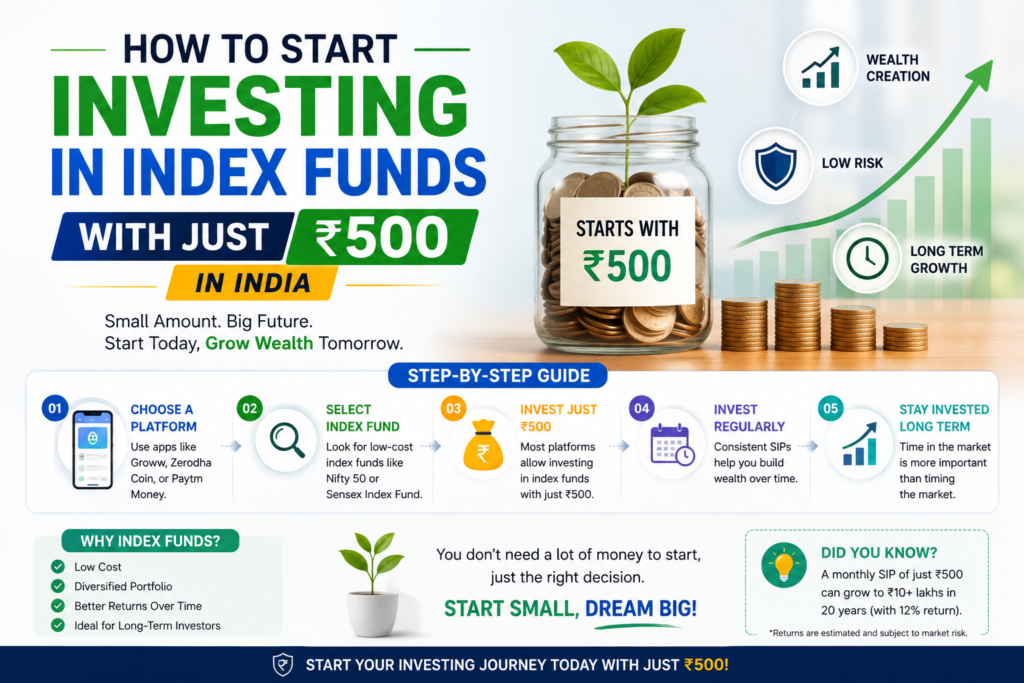
You can start investing in index funds in India with just ₹500. Many beginners believe they need lakhs to begin, but that’s not true. In this guide, I’ll show you 5 easy steps to get started safely.
If you want to start index fund investing with ₹500, you don’t need a large amount of capital or complicated investment strategies. A ₹500 monthly SIP can be a practical starting point for building a consistent investing habit.
Start index fund investing with ₹500 and you can begin building a long-term investment habit without waiting until you have ₹50,000 or ₹1 lakh sitting in your bank account.
You don’t need a huge amount of money to become an investor. If ₹500 is what you can comfortably invest every month, that’s enough to get started with the right approach.
But here’s the thing: simply putting ₹500 into a fund isn’t a complete investment strategy. You need to understand what an index fund does, which index you’re buying, how SIPs work, what costs matter, and what you should realistically expect from a small investment.
Let me break it down simply.
If you’re new to mutual funds, SEBI’s investor education resources explain mutual funds, investment risks and other important concepts in simple terms.
What Is an Index Fund and Why Does ₹500 Matter?
Start index fund investing with ₹500 if your goal is to develop a long-term investing habit while keeping your initial monthly commitment small.
Index funds are different from ETFs in how investors buy and sell them. If you’re confused between the two, our guide on ETF vs mutual funds explains the key differences.
An index fund is a mutual fund designed to track a particular market index instead of actively trying to select stocks that will outperform the market.
For example, an index fund tracking the Nifty 50 aims to provide returns broadly linked to the performance of the companies in that index, after accounting for costs and tracking differences.
Think of it this way:
Instead of trying to guess which one or two companies will become the next big winner, you’re buying exposure to a basket of companies through a single fund.
That’s one reason index funds can be useful for beginners.
But why start with only ₹500?
Because the amount isn’t the only thing that matters.
Your investing habit matters too.
If you can consistently invest ₹500 every month, you’re building a habit. Later, when your income increases, you can increase the amount to ₹1,000, ₹2,000, ₹5,000 or more.
Honestly, I’d rather see a beginner consistently invest an affordable amount than start aggressively with money they might need six months later.
AMFI’s mutual fund investor resources provide useful information about SIPs, KYC, investing and withdrawing from mutual funds.
Can You Really Start Index Fund Investing With ₹500?
Yes, some index funds allow investments or SIPs starting at ₹500.
However, don’t assume every index fund accepts exactly ₹500. Minimum investment requirements can vary between funds and investment options.
Before investing, check:
- Minimum investment amount
- Minimum SIP amount
- The specific index being tracked
- Direct or Regular plan
- Expense ratio
- Tracking difference
And don’t make the mistake of thinking ₹500 will quickly turn into a huge amount of money.
It won’t.
The real advantage is that you’re starting early and creating a repeatable investing process.
If you’re considering a Nifty-based index fund, check the Nifty 50 index methodology to understand how the underlying index is constructed.
How to Start Index Fund Investing With ₹500
Here’s the process I’d follow if I were helping a complete beginner get started.
1. Decide Why You’re Investing
Before selecting an index fund, figure out what the money is actually for.
Are you investing for:
- Long-term wealth creation?
- Retirement?
- A future financial goal?
- Learning how investing works?
Your answer matters because equity index funds are generally intended for long-term investing.
If you’re investing ₹500 today because you need that ₹500 back in three months, an equity index fund may not be the right place for that money.
Simple rule: Don’t invest money you know you’ll need soon just because the market has historically generated attractive long-term returns.
https://investor.sebi.gov.in/hindi/securities-howtoinvest.html?utm_source=chatgpt.com
2. Choose the Index You Want to Track
This is where beginners sometimes get confused.
An index fund isn’t automatically “safe” simply because it’s an index fund. The underlying index determines what you’re actually exposed to.
For example, a broad-market index can provide exposure to many companies, while a sector-specific index concentrates your investment in one particular industry.
If you’re just starting, I prefer keeping things simple rather than buying five different funds because each one sounds interesting.
Look at:
- What index the fund tracks
- How diversified the index is
- Expense ratio
- Tracking difference
- Fund history
- Minimum investment amount
- Minimum SIP amount
You don’t need to become a mutual fund analyst before investing your first ₹500.
But you should know what you’re buying.
3. Understand Direct and Regular Plans
This is something beginners often overlook.
Mutual funds can generally be available as Direct and Regular plans.
A Direct plan is purchased directly from the mutual fund company without a distributor earning a commission from that investment. A Regular plan involves a distributor or intermediary.
Because of this, their expense structures can differ.
If you’re comfortable researching and choosing your own fund, you may want to compare Direct plans before investing.
Don’t select a fund simply because someone on social media calls it “the best.”
Understand the fund first.
You can also refer to SEBI’s mutual fund regulations for the regulatory framework governing mutual funds in India
4. Open Your Investment Account
To invest in mutual funds in India, you’ll generally need to complete the required KYC process and provide the necessary bank and identity details.
You can invest through a mutual fund platform, directly through an asset management company, or another investment service that offers mutual funds.
Once your account is ready, search for the index fund you want.
Double-check the exact fund name before investing.
Different funds can have very similar names, and you don’t want to accidentally select a different scheme.
Before investing, you can also learn more about how to invest in the securities market through SEBI’s investor education material.
5. Start a ₹500 SIP
A SIP allows you to invest a fixed amount regularly instead of trying to invest a large amount at once. If you’re new to SIPs, read our guide on what is SIP and how it works before starting.
Now comes the easy part.
Suppose you’ve decided to invest ₹500 every month in an index fund and the selected fund supports a ₹500 SIP.
You can automate the investment through a Systematic Investment Plan (SIP).
Instead of deciding every month whether you should invest, the money is invested according to your SIP schedule.
For example:
| Month | Investment |
|---|---|
| January | ₹500 |
| February | ₹500 |
| March | ₹500 |
| April | ₹500 |
| May | ₹500 |
| June | ₹500 |
After six months, you’ve invested ₹3,000.
It doesn’t look impressive yet.
And that’s exactly why some people quit.
Investing isn’t exciting every month. The benefit comes from doing the boring thing repeatedly.
6. Don’t Panic When the Market Falls
This is probably more important than choosing between two similar index funds.
Your ₹500 investment won’t move upward every month.
Suppose you invest ₹500 and the market falls. Your investment might temporarily show ₹470, ₹450 or even less depending on market conditions.
Seeing a loss can make a beginner think:
“I made a mistake.”
Not necessarily.
Equity markets move up and down. If your investment is genuinely intended for the long term, temporary declines are part of investing.
When you continue your SIP during falling markets, your fixed investment amount can purchase more units when prices are lower.
But don’t misunderstand this.
Markets don’t necessarily recover quickly, and there are no guaranteed returns.
Your investment horizon and ability to handle volatility still matter.
7. Increase Your SIP When Your Income Grows
This is where your ₹500 investment can become much more meaningful.
Imagine you start with ₹500 per month while earning a modest income.
Later, your salary increases and you can comfortably invest ₹1,000.
Increase the SIP.
Later it becomes ₹2,000.
Increase it again.
This can be more powerful than constantly trying to find an investment that will generate slightly higher returns.
Start small. Increase gradually.
Start index fund investing with ₹500 and increase your monthly investment gradually as your income grows.
How Much Can ₹500 a Month Become?
Start index fund investing with ₹500 and increase your monthly investment gradually as your income grows.
Let’s use an illustrative example.
Suppose you invest ₹500 every month for 20 years.
Your total contributions would be:
₹500 × 12 × 20 = ₹1,20,000
Now imagine, purely for illustration, that the investment generates an average annual return of 10%.
The final value could be considerably higher than the amount you personally contributed because of compounding.
But there’s an important point:
10% is an illustration, not a guaranteed return.
Actual market returns vary.
Some years may be strongly positive. Other years may be negative.
So I wouldn’t look at a ₹500 SIP and ask:
“How rich will I become?”
I’d ask:
“Can I build the habit and increase this amount as my income grows?”
That’s a much more useful question.
What Is Compounding and Why Does It Matter?
Compounding basically means your investment can generate returns, and those returns can themselves contribute to future growth.
Here’s a simple way to think about it.
You invest money.
That money grows.
The growth remains invested.
Over a long period, future growth can build on previous growth.
The longer your investment remains invested, the more time compounding has to work.
That’s why starting with ₹500 at a younger age can be useful compared with waiting several years until you can invest a much larger amount.
Of course, the amount you invest also matters.
Ideally, you want time and increasing contributions working together.
A Realistic ₹500 Index Fund Example
Let’s imagine a 22-year-old beginner named Rahul.
Rahul earns ₹25,000 per month and doesn’t feel comfortable investing a large amount yet.
He decides to start with ₹500 per month in a broad-market index fund.
His first goal isn’t to become wealthy.
It’s simply to invest every month.
After one year, he has contributed ₹6,000.
Later, his salary increases and he increases his SIP to ₹1,000.
A few years later, he increases it again.
That’s a much more realistic investing journey than the social-media story where someone invests ₹5,000 once and supposedly becomes financially free overnight.
Markets don’t work like that.
The combination of regular contributions, time, reasonable investment choices and patience is what makes the strategy practical.
Common Mistakes Beginners Make With Index Funds
1. Choosing a Fund Just Because Its Returns Look High
A fund that performed extremely well recently isn’t automatically the best choice for the next decade.
Look at what the fund tracks and how closely it follows its benchmark instead of chasing the latest performance chart.
2. Investing Money Needed for Emergencies
Your investment portfolio shouldn’t be your emergency cash box.
If you don’t have enough accessible savings and an unexpected expense appears, you could be forced to sell your investment at an inconvenient time.
3. Checking Your Investment Every Day
Seriously, don’t do this.
You’re investing ₹500 for the long term, but you’re checking whether it’s ₹501 or ₹493 every morning.
That behavior can create unnecessary stress and encourage emotional decisions.
4. Buying Too Many Funds
Five index funds don’t automatically make a portfolio better than one well-understood fund.
Beginners often collect funds instead of building a sensible strategy.
Keep your portfolio understandable.
5. Stopping Your SIP During Every Market Crash
Markets falling can feel uncomfortable.
That’s normal.
But if your long-term plan changes every time the market falls, you don’t really have a long-term plan.
Review your investment decision when your goals or financial situation change—not simply because prices moved.
How to Choose a Good Index Fund
You don’t need a complicated spreadsheet with 30 columns.
Start with these checks:
- Underlying index: Know exactly what you’re investing in.
- Expense ratio: Lower costs can matter over long periods, all else being equal.
- Tracking difference: Check how closely the fund has followed its benchmark.
- Fund size and history: Consider these as part of your overall evaluation.
- Minimum SIP: Make sure your ₹500 investment is actually supported.
- Direct vs Regular: Understand the difference before selecting your plan.
Don’t spend three hours comparing tiny differences between funds while ignoring the fact that you haven’t started investing at all.
At the beginner stage, consistency is often the bigger issue.
What Tools Do You Need?
You don’t need expensive software to start.
A basic mutual fund investment platform can help you set up your SIP and monitor your holdings.
You can also use:
- SIP calculator: To understand how different monthly investments and time periods affect hypothetical outcomes.
- Fund factsheets: To examine the fund’s benchmark, expense ratio, holdings and other details.
- Simple spreadsheet: To track your monthly investments and increasing SIP amount.
That’s enough for most beginners.
Should You Invest ₹500 Every Month or ₹6,000 Once a Year?
If your goal is to develop a monthly investing habit, a ₹500 monthly SIP can be easier to maintain financially and psychologically.
You don’t have to wait until you have ₹6,000 available at once.
More importantly, a monthly SIP creates a routine.
However, don’t assume a SIP automatically produces better returns than investing a lump sum simply because it’s called a SIP.
The main benefit for many beginners is discipline and automation.
What If You Can Invest More Than ₹500?
Then you don’t have to stay at ₹500 forever.
For example:
| Monthly SIP | Yearly Contribution |
|---|---|
| ₹500 | ₹6,000 |
| ₹1,000 | ₹12,000 |
| ₹2,000 | ₹24,000 |
| ₹5,000 | ₹60,000 |
The numbers show something simple:
Increasing your contribution as your income grows can have a major impact on your long-term investment value.
So don’t treat ₹500 as the destination.
Treat it as your starting point.
Learn more about long-term wealth creation and how consistent investing can support your financial goals.
When Should You Start?
If you’ve already decided that you want to invest for the long term, waiting for the “perfect” market entry can become an excuse for doing nothing.
At the same time, you shouldn’t blindly invest just because someone says, “Start today or you’ll miss out.”
Get your basic finances organized, understand the product you’re buying, choose an amount you can sustain, and then start.
For someone whose comfortable starting amount is ₹500, there’s nothing wrong with beginning there.
And yes, your first investment might feel almost too small to matter.
That’s okay.
The first ₹500 isn’t supposed to change your life. It’s supposed to change your behavior.
Frequently Asked Questions
Can I start investing in index funds with only ₹500?
Yes, some index funds allow investments or SIPs starting at ₹500. However, minimum investment requirements vary, so check the specific fund before investing.
Is ₹500 enough to start a SIP?
For building an investing habit, yes. ₹500 isn’t a large investment, but it can be a practical starting point. You can increase the SIP as your income grows.
Are index funds safe?
Index funds aren’t risk-free. Equity index funds can fall when the underlying market falls. Their main advantage is broad market exposure and a passive investment approach, not guaranteed returns.
Can I lose money in an index fund?
Yes. The value of an equity index fund can decline, especially over shorter periods. That’s why you should understand market volatility and invest according to your time horizon.
Should beginners invest in one index fund or several?
There isn’t one answer for everyone, but beginners generally don’t need a complicated collection of funds. Start by understanding one suitable index fund before adding more investments.
My Take: Don’t Wait Until You Have More Money
Here’s what I think beginners get wrong about investing.
They believe they need a big amount of money before they can become investors.
You don’t.
If ₹500 is what you can comfortably invest right now, start there.
Learn how the market behaves. Understand your fund. Watch how you react when the market falls.
Then, when your income improves, increase your investment.
That’s a much healthier approach than trying to find some magical investment that turns ₹500 into ₹5 lakh overnight.
And please don’t let social media convince you that slow investing is boring or pointless.
Building wealth usually looks pretty boring while you’re doing it.
That’s not necessarily a bad thing.
Your Simple ₹500 Investing Checklist
Before starting, make sure you’ve done these things:
☐ Decide how much you can comfortably invest every month.
☐ Define your investment goal.
☐ Understand your investment time horizon.
☐ Choose an index you understand.
☐ Compare suitable index funds.
☐ Check the expense ratio and tracking difference.
☐ Check the minimum SIP amount.
☐ Understand Direct vs Regular plans.
☐ Complete the required KYC process.
☐ Set up your ₹500 SIP.
☐ Avoid reacting emotionally to short-term market movements.
☐ Increase your SIP when your income grows.
Final Thoughts
Start index fund investing with ₹500 if that’s the amount you can genuinely afford today.
The important part isn’t making your first investment look impressive.
It’s creating a system you can continue for years.
Your first ₹500 may not make a dramatic difference to your wealth.
But learning to invest consistently, increasing your contributions as your income grows, and staying invested through normal market ups and downs can put you on a much stronger financial path.
If this guide helped you understand how to begin, share it with someone who keeps saying, “I’ll start investing when I have more money.”